How to Use This Checklist
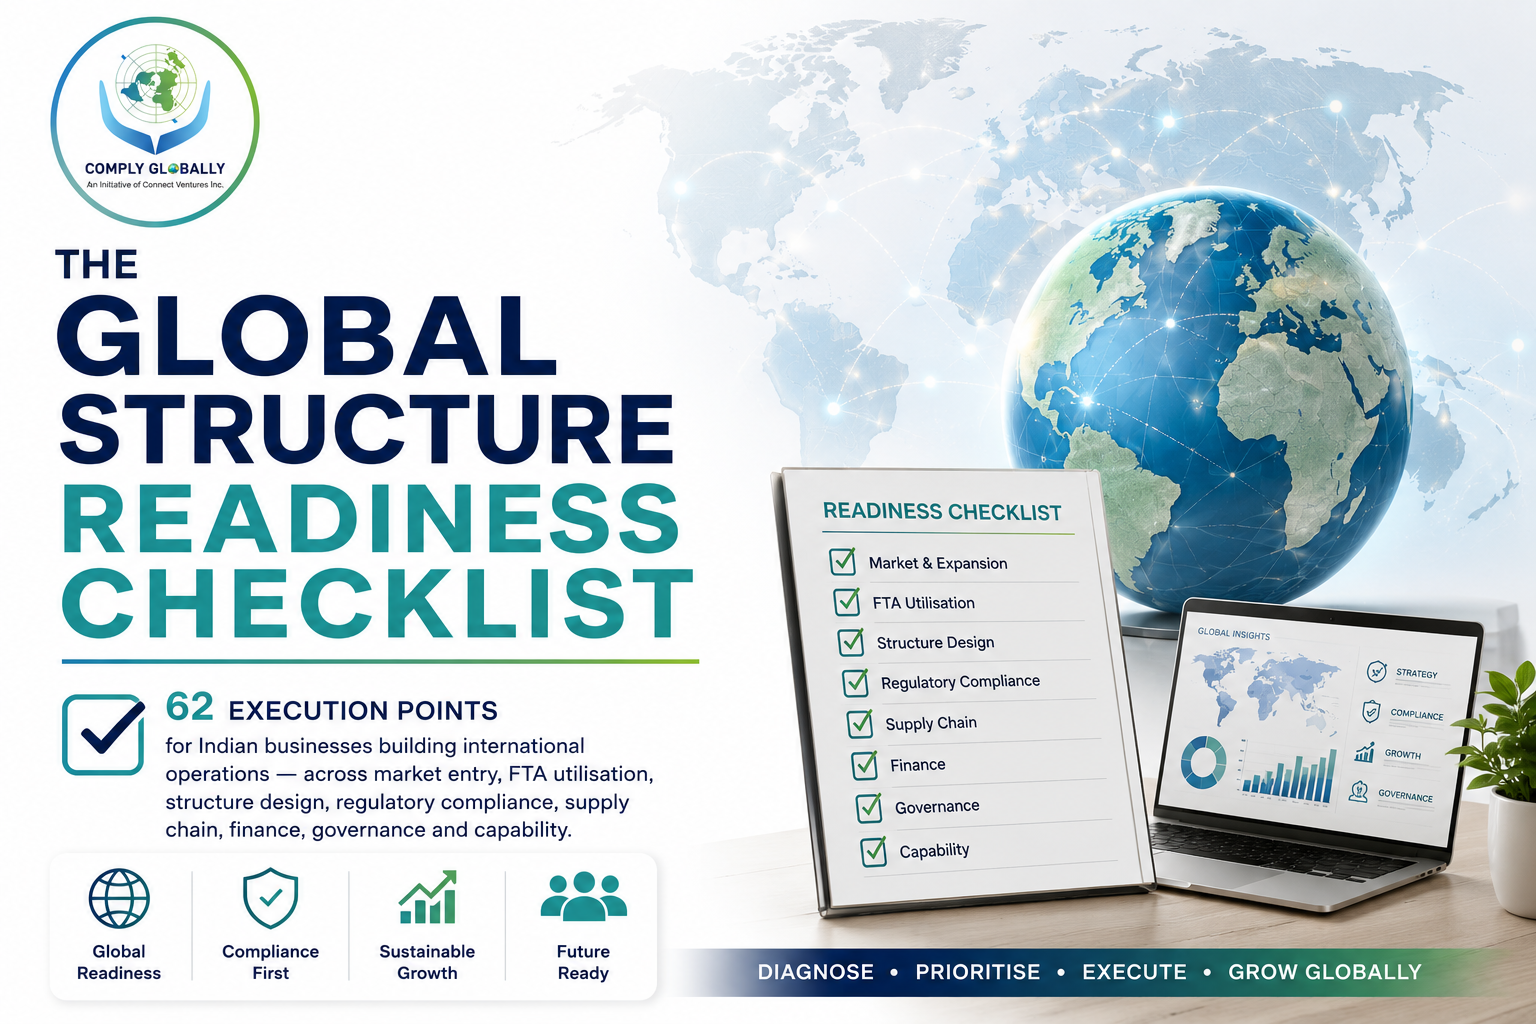
This is a diagnostic, not a to-do list. It shows you where your international operation is exposed, quickly and in front of the people who can fix it.
Global Structure exporters score well in Sections A, E and F, and poorly in B, C, D and G. That pattern is itself the finding: Indian businesses tend to be strong on market and logistics execution and weak on trade preference capture, structure design and buyer-facing governance, which is precisely where the margin and the lost tenders sit.
Scoring
1. Work through each section and mark only the items you could evidence today, in a meeting, without preparing anything first. If it would take a week to produce, it is not a tick.
2. Record an owner and a target date against every unticked item. An item without a named owner will not move.
3. Count your ticks and read your band on the reverse of the final page.
4. Re-run the diagnostic quarterly. The trade environment now changes faster than an annual planning cycle.
A NOTE ON SCOPE
Sections C and D touch on overseas direct investment under FEMA, transfer pricing, permanent establishment risk, place of effective management and global minimum tax. These are diagnostic prompts to check whether a question has been considered. They do not replace jurisdiction-specific advice on your facts. Structures are far easier to establish than to unwind, and unwinding is where the tax generally arises.
A Market & Expansion Readiness
Where you sell, how you sell there, and whether the model matches the market.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Identify three to five priority markets with a stated rationale for each — demand, agreement coverage, competitive position — rather than historical accident. | ||
| ☐ | Set an explicit board-agreed ceiling on revenue exposure to any single market, and report against it monthly. | ||
| ☐ | Choose a go-to-market model per market: direct export, distributor, agent, joint venture or local entity. Record why. | ||
| ☐ | Map buyer expectations market by market: invoicing currency and entity, lead time, service level, warranty response, returns handling. | ||
| ☐ | Identify deals lost in the last 24 months where the stated or suspected reason was the absence of a local entity, local invoicing or local support. | ||
| ☐ | Quantify the duty saving available in each priority market under an applicable agreement, in currency, not percentage. | ||
| ☐ | Assess whether your product requires local certification, testing, labelling or homologation before first shipment. | ||
| ☐ | Confirm whether public-sector or large-enterprise buyers in each market can onboard a foreign-registered vendor at all. |
B FTA & Preferential Trade Utilisation
This is the fastest available margin in most Indian exporters, and the least owned. Indian utilisation runs at 20–30% of eligible exports against 60–70% for partner-country exporters shipping into India.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Appoint one named individual accountable for preference utilisation, with the claimed-preference percentage on the monthly management dashboard. | ||
| ☐ | Calculate your current utilisation rate: value shipped under preference divided by value eligible for preference, per agreement. | ||
| ☐ | Validate HS classification for every SKU in every destination market — classification differences between markets are a common and expensive silent error. |
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Confirm the applicable rule of origin for each product-market pair: change in tariff heading, regional value content, specific process, or a combination. | ||
| ☐ | Build and maintain a value-addition calculation per product that can be reproduced on demand, with source documents attached. | ||
| ☐ | Establish a document retention protocol capable of supporting a verification request three to five years after shipment. | ||
| ☐ | Assess the India–UK CETA schedule for your product lines following entry into force on 15 July 2026, including the Double Contribution Convention position on posted staff. | ||
| ☐ | Prepare for India–EU FTA implementation now rather than at ratification: classification, origin and documentation lead time exceeds the ratification window. | ||
| ☐ | Compare the cost of claiming preference against the preference margin per lane, and shipment under standard rates where the margin does not justify it — deliberately, not by default. |
C Structure & Jurisdiction Design
Where you make it, where you bill it and where you bank it are three separate decisions. Most Indian exporters still treat them as one.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Articulate your three addresses today: production, contracting and capital. Note where all three sit in a single entity. | ||
| ☐ | For each priority market, decide explicitly whether the contracting address should differ from the production address — and record the commercial reason. | ||
| ☐ | Name the specific commercial failure any proposed overseas entity is intended to solve, in language someone in sales would recognise. | ||
| ☐ | Match the jurisdiction to the purpose: demand access, bloc access, distribution and re-export, IP and capital, or low-friction administration. One entity rarely serves two purposes well. | ||
| ☐ | Model the full annual carrying cost of the proposed entity in a year in which it generates no revenue — filings, audit, substance, banking, local directorship, registered office. |
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Identify who will actually direct the overseas entity, from where, and how that direction will be evidenced. | ||
| ☐ | Define the exit path before incorporation: how the entity would be wound up, what it would cost and what tax would arise. | ||
| ☐ | Determine where intellectual property should sit, and whether any transfer would trigger a valuation or exit charge. |
D Legal, Tax & Regulatory Compliance
The section that separates structures which survive the first assessment from structures built for a pitch deck.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Confirm the overseas direct investment route under FEMA for the proposed investment, and the approvals required before remittance. | ||
| ☐ | Establish the reporting calendar for overseas investment: identification number, initial filing and annual performance return. | ||
| ☐ | Document a transfer pricing policy covering every intercompany flow — goods, services, royalties, management fees, guarantees, loans — with benchmarking maintained contemporaneously. | ||
| ☐ | Assess permanent establishment exposure created by field engineers, project sites, dependent agents and long-duration onsite work. | ||
| ☐ | Test place of effective management: could a company incorporated abroad but directed from India be assessed as an Indian tax resident? | ||
| ☐ | Map withholding tax on cross-border service and royalty invoices, and confirm treaty relief eligibility and the documentation required to claim it. | ||
| ☐ | Confirm economic substance requirements in the chosen jurisdiction and whether current plans satisfy them. | ||
| ☐ | Establish whether the group falls within the global minimum tax framework and, if so, what additional reporting follows. | ||
| ☐ | Confirm indirect tax registration and filing obligations in each market: VAT, GST or sales tax, including marketplace and distance-selling rules. |
E Supply Chain & Operations
Resilience is no longer the opposite of efficiency. It is the price of staying efficient.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Diversify the sourcing base for critical inputs — identify every single source dependency and its replacement lead time. | ||
| ☐ | Establish a regional warehousing or forward-stocking strategy for markets where lead time is losing you orders. | ||
| ☐ | Evaluate logistics partners on multi-market reach and customs capability, not freight rate alone. | ||
| ☐ | Size buffer inventory per key market against a defined disruption scenario, not against last year’s average. | ||
| ☐ | Assess geopolitical and chokepoint risk on your primary shipping routes, and cost the alternative routing in advance. | ||
| ☐ | Implement shipment-level tracking with exception alerting, so delays surface before the customer raises them. | ||
| ☐ | Quantify demurrage, detention and documentation delay cost over the last four quarters as a single number. | ||
| ☐ | Establish a customs broker review: are classifications, valuations and origin claims consistent across ports and agents? |
F Financial & Banking Readiness
Most of the competitiveness gap sits in the nine landed-cost lines that are not duty.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Rebuild the landed-cost model line by line per market, separating duty from the operating-model lines. | ||
| ☐ | Formalise a foreign exchange policy: hedge ratio, tenor, instruments and the authority to transact. | ||
| ☐ | Enable multi-currency invoicing and collection in the currencies your buyers prefer to pay in. | ||
| ☐ | Confirm trade finance capacity — letters of credit, bank guarantees, export credit — against your target order book, not your current one. | ||
| ☐ | Quantify banking spreads and correspondent charges on cross-border flows, and benchmark against alternatives. |
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Review credit terms extended by market and test how much of the concession is attributable to foreign-supplier risk perception. | ||
| ☐ | Assess export credit insurance and available government financing schemes against current exposure. |
G Governance, ESG & Buyer Diligence
Compliance is now a gate, not a preference. Buyers settle it before price is discussed.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Assemble a standing buyer-diligence pack that can be produced within one week: corporate structure, beneficial ownership, financials, certifications, policies, insurances. | ||
| ☐ | Publish an anti-bribery and anti-corruption policy with evidence of training and a working reporting channel. | ||
| ☐ | Establish supply chain labour standards documentation — now a live tariff and market-access exposure, not only a reputational one. | ||
| ☐ | Confirm data protection compliance for every market where you hold or process customer data. | ||
| ☐ | Prepare ESG and sustainability reporting to the standard your largest buyer’s procurement function actually requests. | ||
| ☐ | Maintain a single board-level register of regulatory obligations by jurisdiction, with owners and filing dates. | ||
| ☐ | Run an internal test: request the full diligence pack unannounced and record how long it takes to produce. |
H Organisational Capability
Global expansion is a capability, not a project. Projects end.
| A C T I O N | O W N E R | T A R G E T D A T E | |
| ☐ | Create a defined export strategy function with a named leader, however small. | ||
| ☐ | Train commercial and finance teams on rules of origin, classification and preference claims — not only the logistics team. | ||
| ☐ | Run two geopolitical scenarios a year with numbers attached: a re |
| A C T I O N | O W N E R | T A R G E T D A T E | |
| forecast with recorded decisions, not a workshop. | |||
| ☐ | Track performance beyond export volume: margin per market, order to-delivery time, preference capture rate, market penetration. | ||
| ☐ | Establish structured customer feedback loops per market feeding product and packaging adaptation. | ||
| ☐ | Review this checklist quarterly at management level and record movement against the previous score. |
D I A G N O S T I C
Read Your Score
Count only the items you could evidence today, without preparation.
| S C O R E | B A N D | W H A T I T M E A N S |
| 0 – 20 | Exporter | You sell abroad. You are not yet structured to operate abroad. Concentration risk and unclaimed preference are almost certainly your two largest recoverable losses. Start with Section B — it costs least and returns fastest. |
| 21 – 35 | Transitional | The commercial model has outgrown the corporate structure. Typical symptoms: stalled vendor onboarding, withholding tax leakage, distributors owning your customers. Sections C and D are the priority. |
| 36 – 50 | Structured | A workable international operation with identifiable gaps, usually in preference capture and buyer-facing governance. Sections B and G will produce the next margin step. |
| 51 – 62 | Globally operating | You are structured to withstand a policy reversal rather than react to one. Maintain the quarterly cycle — this score decays without it. |
THE ONE NUMBER WORTH ACTING ON THIS QUARTER
If you take a single item from this document, take Section B, item 2: calculate your preference utilisation rate. Indian exporters claim preferences on 20–30% of eligible exports. Partner-country exporters shipping into India claim at 60–70%. Closing the gap requires no new customer, no new product and no capital expenditure. It needs only classification discipline, defensible origin and documentation that survives an audit. For help checking your own rate, see Global Business Compliance.
More guides
For an overview, see our full list of services: Service.
All Business Expansion articles: Business Expansion guides.